The Small Business Cash Flow Playbook for 2026
A profitable business can still run out of money. The gap between earning a sale and holding the cash is where most small companies get into trouble, and it is a gap you can measure, forecast and manage. This playbook sets out the routine we would install in any owner-run business.
Profit and cash are not the same number
An invoice is not money. When you record a sale, accounting profit recognises revenue that may not arrive for 30, 60 or 90 days, while wages, rent and supplier payments leave the account on a fixed schedule. A company can show a healthy profit and still miss payroll because the timing does not line up.
The first step is to stop treating the bank balance as a scorecard and start treating it as a schedule. List every payment you expect in the next three months with a date, not just an amount. Then list every payment you owe. The difference between those two lists, week by week, is the number that decides whether you sleep well.
Map your cash conversion cycle
The cash conversion cycle measures how long your money is tied up before it returns. Add the days inventory sits on the shelf to the days customers take to pay, then subtract the days you take to pay suppliers. If the result is 70 days, you are financing 70 days of operations out of your own pocket or your credit line.
Write the three numbers down for your own business. Most owners know roughly how long customers take to pay, but far fewer know their true inventory days or their real payable terms once early-payment discounts are counted. You cannot shorten a cycle you have never measured, and even a ten-day improvement can be worth more than a small loan.
Related reading: releasing cash trapped in inventory pairs well with Working Capital.
Forecast 13 weeks, not 12 months
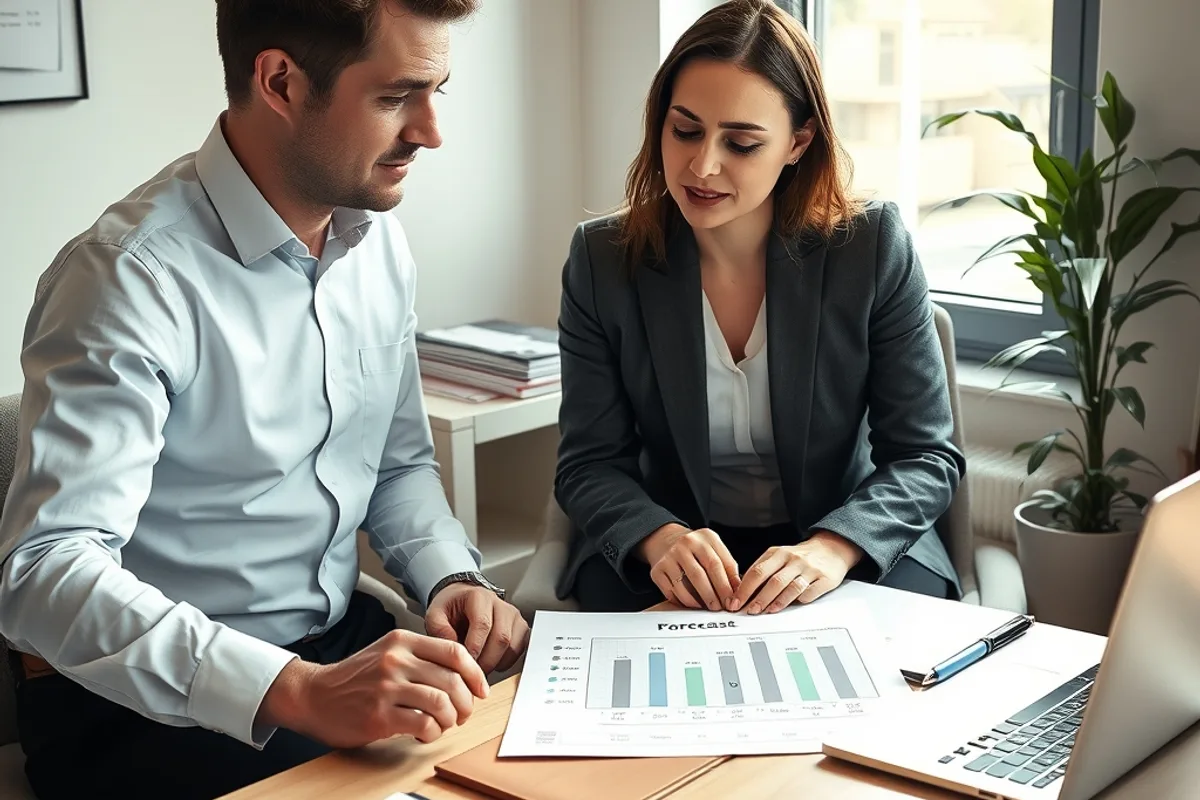
Annual budgets are useful for direction and useless for weekly decisions. A rolling 13-week forecast covers one quarter in enough detail to see trouble coming while there is still time to act. Update it every Monday with actual bank movements and push the horizon forward one week.
Keep the forecast simple: opening balance, expected receipts, committed payments, and closing balance. Mark receipts as confirmed, likely or optimistic, and run the forecast on the confirmed column first. If that version shows a shortfall, you have a real problem to solve rather than a spreadsheet to argue with.
A profitable business can still run out of money. The bank balance is a schedule, not a scorecard.
Tighten receivables without damaging relationships
Slow payment is often a process problem rather than a customer problem. Invoices sent late, missing purchase order numbers or unclear payment instructions all add days. Send invoices the same day you deliver, confirm the person who approves them, and make bank details impossible to miss.
Then make paying early attractive rather than making paying late painful. A small discount for payment within ten days often costs less than the interest on a credit line. Automated reminders before the due date, a short phone call at seven days overdue and a clear escalation path will recover more cash than an aggressive letter sent at 60 days.
Also see our guide to how invoice finance actually works for a deeper comparison.
Time your payables deliberately
Paying suppliers early feels virtuous, but it is effectively an interest-free loan to them. If your supplier offers a genuine discount for early settlement, calculate the annualised return before accepting. A 2 percent discount for paying 20 days early is worth far more than most savings accounts, but only if you have the cash to spare.
If you do not have the cash, pay on the agreed date and not before. Negotiate terms openly when you sign a contract rather than stretching payments later without warning. Suppliers forgive a clear conversation about timing; they remember being surprised, and they price that risk into the next order.
Background: how cash flow differs from profit.
Build a buffer before you need it
Every business needs a cash buffer, but the right size depends on volatility rather than ambition. A company with recurring subscription revenue can hold less than one with seasonal project work. Start with four weeks of fixed costs and build towards eight or twelve as profits allow.
Keep the buffer in a separate account so it is visible but inconvenient to spend. The purpose is not to earn a return; it is to buy you the time to make a calm decision when a large customer pays late or a piece of equipment fails. A buffer used once has already paid for itself.
Review monthly and act early
Set a fixed monthly review with three questions: what changed in the forecast, which customer or supplier moved the number, and what will we do before the next review. Keep the meeting to 45 minutes and base it on the same report every time so trends are visible.
The businesses that survive downturns are rarely the ones that predicted them perfectly. They are the ones that noticed within weeks rather than quarters and cut or renegotiated while they still had options. Cash management is not a finance department ritual; it is the operating rhythm of the company.
- A 13-week rolling cash forecast gives enough warning to act before a shortfall becomes a crisis.
- Cash conversion cycle equals inventory days plus receivable days minus payable days.
- Invoices sent the same day are usually paid faster than invoices chased later.
- A 2 percent discount for paying 20 days early can be worth more than most savings rates.
- Keep four to twelve weeks of fixed costs in a separate buffer account.